 aktiv_admin
Assessing Scuba Diving Insurance: General Travel Policies vs. Specialist Cover
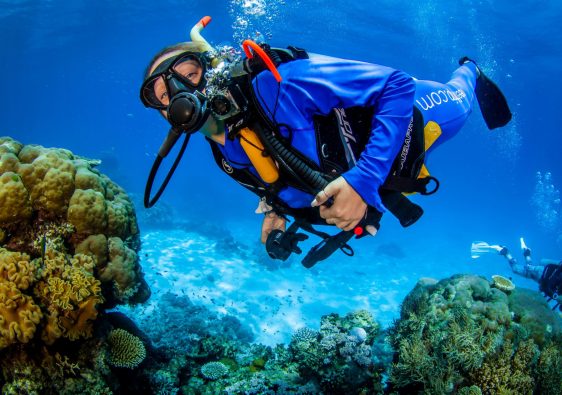
For professionals in travel and leisure, understanding insurance for specialized activities like scuba diving is critical. While many use general travel insurance, such as Travel Guard, specific underwater risks often fall outside standard provisions. This analysis compares these with dedicated specialist dive insurance, guiding evaluation for adequate protection.
General Travel Insurance for Divers: Limitations
General travel insurance, exemplified by Travel Guard, primarily addresses common travel disruptions: trip cancellation, non-extreme sport medical emergencies, and baggage loss. Its broad appeal serves the average traveler. However, scuba diving, categorized as ‘adventure’ or ‘high-risk,’ introduces specific medical challenges that typically exceed these policies’ default parameters. Policy wordings often contain explicit exclusions or stringent conditions for diving incidents.

Common exclusions include dives beyond specific depth limits (e.g., 60 feet/18 meters), technical diving, cave diving, wreck diving, or uncertified diving. Specialized medical treatment for diving-related injuries like decompression sickness (DCS), including hyperbaric chamber therapy and associated medical evacuation, is frequently excluded or severely limited. Relying solely on general policies for scuba diving risks significant financial liability. Policyholders must meticulously review "hazardous activities" clauses.
The Imperative of Specialist Dive Insurance
Specialist dive insurance providers (e.g., DAN, DiveAssure) are purpose-built for scuba diving risks. Their policies are framed around diving emergencies, offering unparalleled coverage for incidents like DCS, arterial gas embolism (AGE), and other barotrauma. These policies cover the full spectrum of medical care: immediate oxygen, evacuation, hyperbaric chamber treatments, physician fees, and post-treatment expenses. Coverage precisely aligns with diving accident medical protocols.
Specialist policies often include worldwide coverage, direct payment to hyperbaric facilities, and 24/7 emergency hotlines staffed by dive medical professionals, ensuring rapid, appropriate care. They typically cover non-medical emergencies like dive equipment damage/loss, dive trip interruption due to medical reasons, and liability. They also accommodate varying diving levels without general policy restrictions, provided the diver is certified and within training limits.
Comparative Analysis and Strategic Integration
The core difference lies in risk assessment. General policies exclude high-risk activities; specialist policies include standard, certified diving. A Travel Guard policy might cover a broken leg, but likely not full hyperbaric treatment for DCS. Such treatments can cost tens of thousands, making any coverage gap catastrophic.
Professionals should consider strategic integration. General travel insurance covers "travel" aspects (flights, accommodation, general health, baggage); specialist dive insurance specifically covers "dive" aspects. For frequent divers, an annual specialist policy is often most cost-effective, complemented by standard travel insurance for non-diving risks. This layered approach mitigates financial exposure, protecting against both common travel mishaps and specific diving emergencies.
| Coverage Aspect | General Travel Insurance (e.g., Travel Guard) | Specialist Dive Insurance (e.g., DAN, DiveAssure) |
|---|---|---|
| Medical Evacuation (Dive-Related) | Often limited or excluded for diving accidents; may require pre-approval; significant out-of-pocket risk for specialized transport. | Comprehensive, direct medical evacuation for diving injuries; includes specialized transport to appropriate medical facilities. |
| Hyperbaric Chamber Treatment | Typically excluded under ‘hazardous activities’ clauses or subject to strict limits; high likelihood of no coverage. | Full coverage for hyperbaric treatments, including facility fees, physician charges, and associated medical costs. |
| Depth Limits & Activity Restrictions | Commonly restricts coverage beyond recreational limits (e.g., 60-100 ft); excludes technical, cave, or wreck diving. | Covers recreational diving up to certification limits; often offers options for technical diving, provided proper certification. |
| Dive Equipment Damage/Loss | May fall under general baggage coverage with low limits and high deductibles; specific dive gear often not itemized. | Specific coverage for dive gear damage, loss, or theft; higher limits and tailored to value of equipment. |
| Dive Trip Interruption/Cancellation (Medical) | May cover general medical trip interruption; specific dive-related medical reasons often not a primary trigger for specific dive activity reimbursement. | Covers interruption or cancellation directly due to a covered diving accident or medical emergency preventing diving. |
| 24/7 Emergency Assistance | General travel assistance line; may not have dive medical expertise. | 24/7 emergency hotline staffed by dive medical professionals (e.g., DAN medics), providing immediate expert guidance. |
"General travel insurance policies are crafted for the typical tourist, not the niche enthusiast. While they provide a safety net for common misfortunes, the specific, high-cost medical needs associated with diving accidents—like hyperbaric therapy—are almost universally outside their primary scope, often relegated to an exclusion clause that few recreational divers fully scrutinize." – Dr. Anya Sharma, Risk Management Consultant, Leisure Travel Sector
"For any individual engaging in scuba diving, regardless of experience level, specialist dive insurance is not merely an option; it is a fundamental pillar of responsible diving. The tailored medical expertise, direct billing to hyperbaric facilities, and comprehensive coverage for decompression sickness are protections that no general travel policy can genuinely replicate. It’s an investment in your safety and financial security underwater." – Captain Ben Carter, Marine Safety and Dive Operations Expert
Verdict/Recommendation
For divers and industry professionals, the conclusion is clear: relying solely on general travel insurance like Travel Guard for scuba diving risks is insufficient. While valuable for general travel contingencies, such policies have limitations and exclusions for specialized activities, leaving critical gaps in diving emergency protection. The definitive recommendation is to secure a dedicated specialist dive insurance policy (e.g., DAN, DiveAssure). This ensures comprehensive coverage for dive-specific medical emergencies, hyperbaric treatment, and specialized evacuation. For complete peace of mind, combine this specialist coverage with a general travel insurance policy to cover non-diving risks, creating a robust, multi-layered strategy that truly protects the diver.
FAQ Section
Are all scuba diving activities covered equally by specialist policies?
No, specialist policies differentiate. Recreational diving within certification limits is generally covered. Extreme forms like technical, cave, or commercial diving often require specific add-ons or higher-tier policies. Divers must verify explicit coverage for their intended diving type, including depth limits and equipment, to avoid gaps.
What if I only dive once or twice a year? Is specialist insurance still necessary?
Yes, critically important. Diving risks, especially decompression sickness, don’t depend on frequency; a single incident can incur exorbitant medical costs. Many specialist providers offer flexible short-term or trip-specific policies, cost-effective for occasional divers, ensuring essential protection without long-term commitment.
Can I combine a general travel policy with specialist dive insurance for comprehensive coverage?
Yes, combining general travel and specialist dive insurance is the most recommended strategy. General policy covers broader travel risks (cancellation, lost luggage, non-diving medical issues). Specialist dive insurance addresses all dive-related medical emergencies, evacuations, and equipment. This layered approach ensures all eventualities are managed by tailored policies, optimizing coverage and cost-effectiveness.